Author: Zhou, ChainCatcher
After the US stock market closed on October 15th (Eastern Time), index provider MSCI announced that it had officially adopted the exclusion rule for non-operating companies. The new rule will take effect after the market closes on November 30th.
According to the potential impact list released by MSCI along with the announcement, Strategy, the world's largest publicly traded company with Bitcoin holdings, is among those proposed for removal, as is Metaplanet, a Japanese Bitcoin treasury company. The final list will be announced on November 11.
Strategy's stock closed at $151.29, up 5.62%. After the announcement, the stock fell 1.60% to $148.87 in after-hours trading, and the decline widened to 2.54% in overnight trading by the early morning of October 16th, Eastern Time.
Compared to a year ago, the reaction this time is calm. In November 2025, Strategy's stock price fell for weeks based solely on a research report from JPMorgan Chase regarding the risk of being excluded from the MSCI index. Now that the rules have been officially implemented, why is there no panic in the market, and what exactly does being excluded from the MSCI index mean?
MSCI's new regulations have been implemented, making it difficult for Strategy to pass.
This marks the second time MSCI has targeted such companies. On October 10, 2025, MSCI initiated a consultation proposing to exclude companies with digital assets accounting for more than 50% of their total assets from the Global Investable Market Index, and to implement temporary measures for companies on the list, including freezing the number of shares and increasing the inclusion factor, and temporarily suspending new inclusions.
JPMorgan Chase subsequently estimated that if Strategy were removed from the MSCI index, passive funds tracking the index alone could see an outflow of $2.8 billion. Strategy's stock price subsequently came under continued pressure, falling approximately 71% from its November 2024 high by the end of 2025.
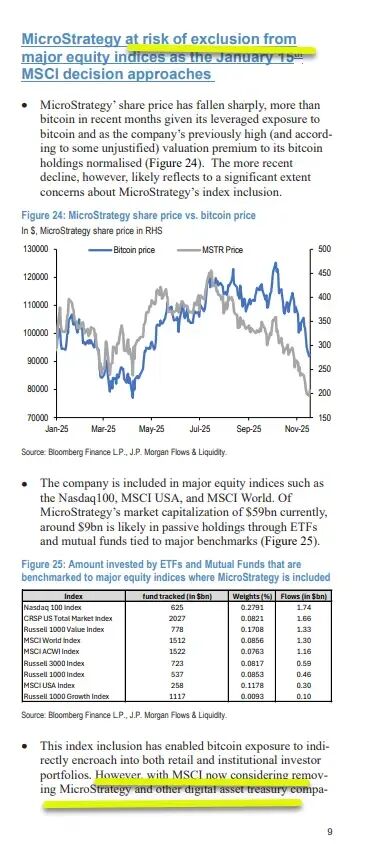
On January 6, 2026, MSCI announced that it would not implement the proposal in the February index review, and Strategy's stock price rose by about 6% in after-hours trading. However, the temporary measures were retained, and MSCI also stated that it would conduct a broader review of non-operating companies.
On August 3, a new round of consultations was launched. The new plan no longer mentions digital assets and instead uses a two-step screening process. The first step checks whether operating assets exceed 50% of total assets; those that pass are retained directly. Those that fail proceed to the second step, where they are assessed based on five financial ratios: operating asset strength, expense strength, operating cash flow, fair value strength, and capital dependence. Those that fail four or more of these ratios are disqualified from inclusion.
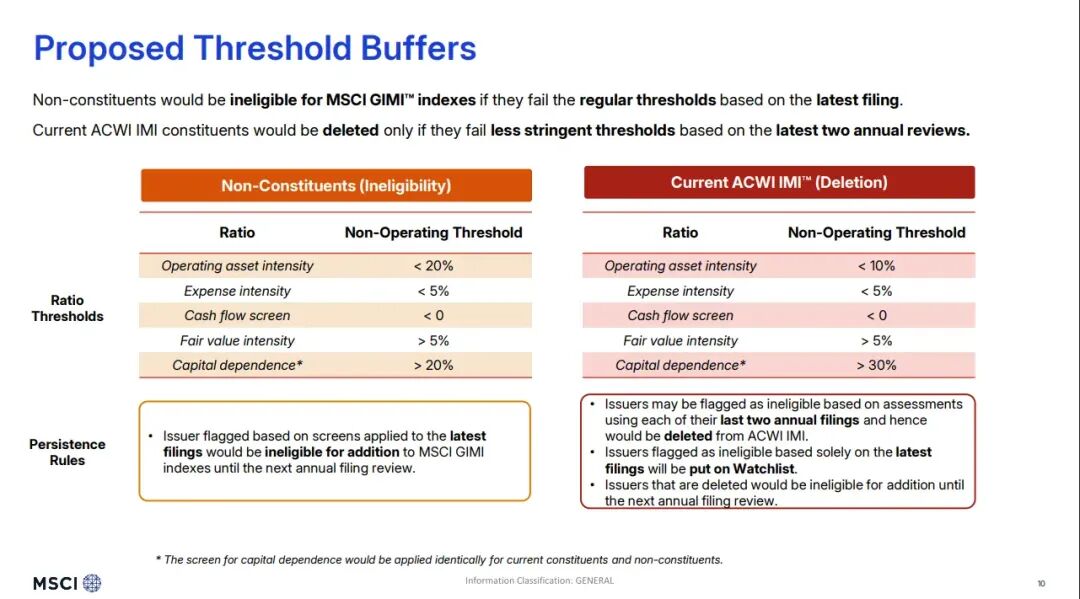
To reduce index turnover, MSCI has implemented a buffer for existing constituent stocks. According to the August consultation document, the eligibility criteria for constituent stocks have been relaxed, with the operating asset strength standard lowered from below 20% to below 10%, and capital dependence from above 20% to above 30%. A constituent stock will only be removed if it fails the screening process in the two most recent fiscal years; only those failing in the most recent period will be placed on a watch list.
MSCI explained in its consultation paper that only ongoing changes in business structure should trigger a reclassification; a one-time failure to meet the criteria will not. This announcement states that the final proposal is a minor adjustment to the August proposal, with specific thresholds detailed in its methodology appendix. Companies removed will be removed from the MSCI Global Investable Markets Indexes and will not be eligible for re-inclusion until the next annual review.
With the implementation of the new regulations, the temporary measures targeting digital asset treasury companies will also be terminated during the index review in November, and these companies will be uniformly evaluated using the new method from now on.
The consultation paper in August, using May data as a model, resulted in 3 companies being removed from the list and 3 being placed on the watch list. The list released with this announcement is based on financial data as of September 30th and market capitalization as of October 9th, expanding the scope to 5 companies proposed for removal and 17 companies placed on the watch list. Besides Strategy and Metaplanet, those proposed for removal include UK uranium holder Yellow Cake, Icelandic investment company Skel fjárfestingafélag, and Solana treasury company Upexi.
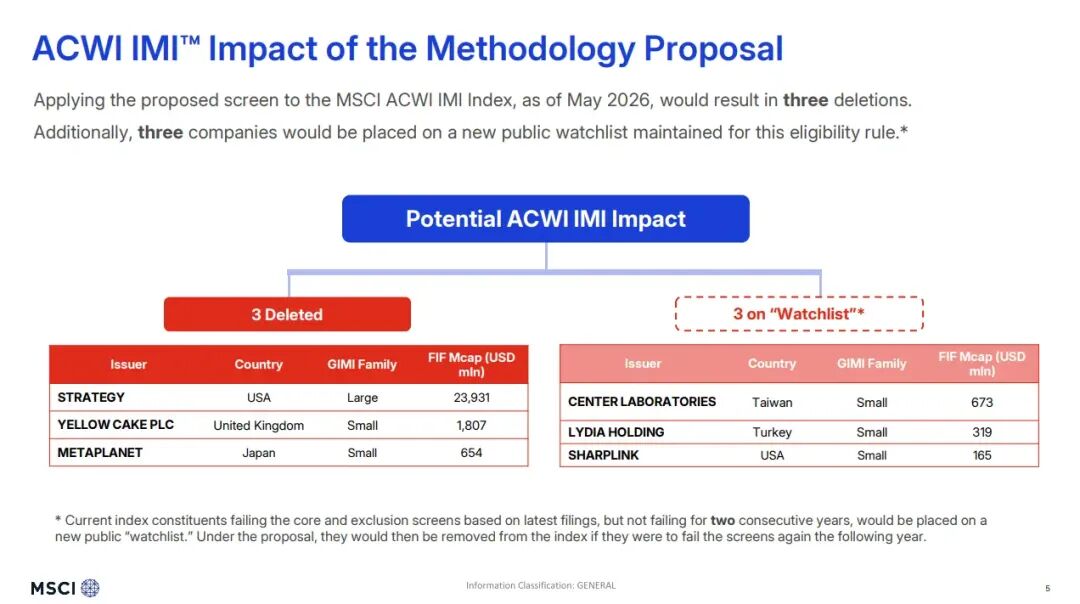
The new regulations are written in a neutral tone regarding asset types, but Strategy is finding it difficult to pass, with the crux of the problem lying in two of the tests.
According to MSCI's definition, capital dependence equals cash flow from financing activities divided by total assets, and the company must have engaged in financing activities to accumulate assets within the past 12 months. According to Strategy's annual reports, its cash flow from financing activities in fiscal years 2024 and 2025 was approximately $22.13 billion and $24.84 billion, respectively, corresponding to year-end total assets of approximately $25.84 billion and $61.64 billion, representing ratios of approximately 86% and 40%, respectively. Both years, these ratios far exceeded the 30% threshold for constituent stocks.
The standard for the cash flow test is negative operating cash flow. Strategy's operating cash flow for fiscal years 2024 and 2025 was approximately negative $53 million and negative $67.2 million, respectively, also triggering the threshold for two years. According to this calculation, the two-year buffer is unlikely to provide sufficient protection for Strategy, which explains why it was directly placed on the removal list in the May simulation, rather than the watch list.
The pace of fundraising has not slowed down this year. According to Strategy's 8-K filing in September, the company has raised approximately $20.9 billion this year through the issuance of common and preferred stock, ranking fourth in terms of the size of its stock offerings in the United States, behind only SpaceX, Alphabet, and Intel.
Whether the other three criteria apply depends on whether Bitcoin is considered an operating asset, which is the core of the dispute. MSCI described the common characteristics of non-operating companies in its consultation paper: they create value by accumulating and holding non-operating assets, their own business generates almost no cash, their performance is driven by market fluctuations, and they rely on external capital rather than their own operations to achieve growth.
In its open letter to MSCI in September, Strategy emphasized that the company employs approximately 1,500 people globally. Following discussions with SEC officials, its Bitcoin business is disclosed as an operating segment under US GAAP, with related profits and losses recorded as operating expenses. Strategy argues that the distinction between operating and non-operating activities is not defined under US GAAP, IFRS, or any other recognized legal framework. The new proposal is merely a different way of repackaging the plan withdrawn in 2025, ultimately leading to the same result.
Two days ago, Saylor stated that MSCI's stance to date has been disappointing, imposing biased value judgments on digital assets, and hoped that MSCI would reconsider. He also announced that the bear market in the crypto market over the past year has ended, and Bitcoin will return to above $100,000.
The Bitcoin Policy Institute (BPI) also released a report questioning MSCI's decision-making process. The report points out that metadata shows the presentation materials MSCI used for this consultation were stored in an internal folder specifically for digital asset treasury companies.
Of the 17 companies on the latest watch list, most are digital asset treasury companies, including Ethereum treasury company SharpLink, as well as Ton Strategy, Solana Company, DeFi Development, and Sui Group. However, the list of companies to be removed or placed on watch also includes uranium holders, Icelandic investment companies, and several investment holding companies from Canada, Sweden, and Israel.
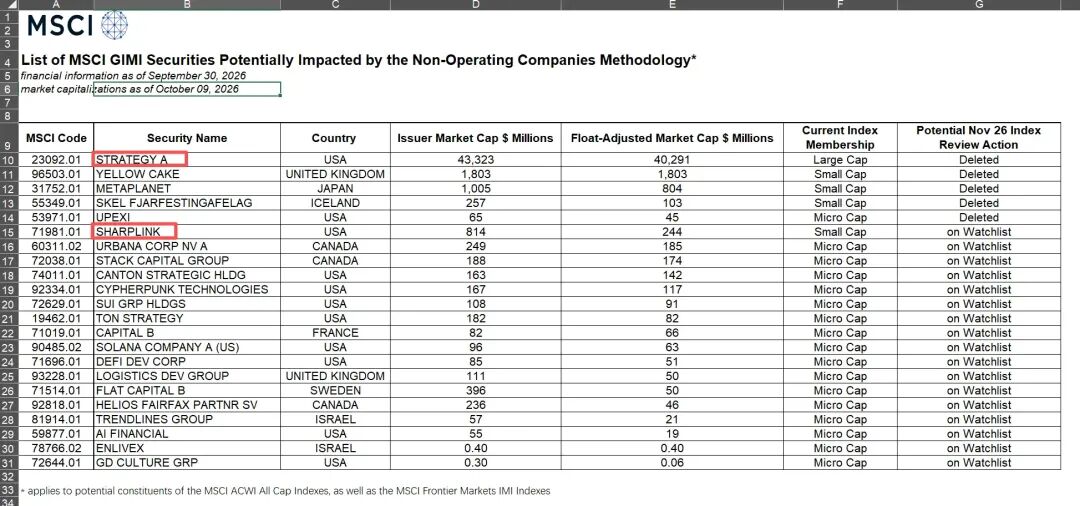
The real disparity lies in size. According to the list, the combined free-float adjusted market capitalization of the 22 companies is approximately $44.4 billion, with Strategy accounting for about $40.3 billion, or roughly 91%. The rules apply equally to all companies, yet the vast majority of the impact falls on Strategy alone.
Limited passive selling pressure? The real pressure comes from the financing flywheel.
The most direct consequence of being removed from the index is a sell-off by passive funds. JPMorgan Chase estimated last November that Strategy might face a $2.8 billion outflow if removed from MSCI; if other index providers follow suit, the total outflow could reach $8.8 billion.
Of this, $2.8 billion comes from funds tracking the MSCI World, MSCI ACWI, and MSCI USA indices, amounting to approximately $1.3 billion, $1.16 billion, and $300 million respectively. The remaining $8.8 billion includes the Nasdaq 100, the CRSP U.S. Total Index, and the Russell series, with the Nasdaq 100 alone accounting for approximately $1.74 billion, provided multiple index providers act simultaneously.
However, JPMorgan's estimate is based on MSCI's proposal last year, and is also based on the market capitalization and index weights at that time.
Strategy's own assessment is much more conservative. The company stated on its MSCI website that the proposal will not have a substantial impact on Strategy, as funds tracking the MSCI World Investable Market Index hold only 3.1% of its underlying shares, approximately 13 million shares—less than a single trading day's worth of trading volume.
According to Bitcoin analyst Adrian Morris, MSTR's average daily trading volume this year is about $2.91 billion. The $2.8 billion sell-off is equivalent to about 0.96 trading days' worth of trading volume, which is only 18.3% of last week's trading volume.
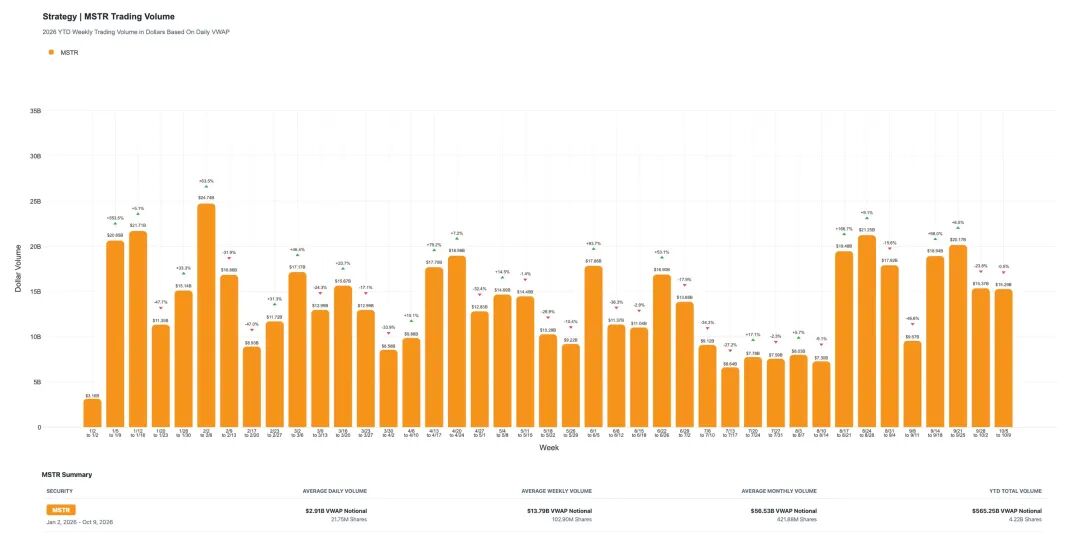
However, the selling pressure from index adjustments is usually concentrated at the close of trading on the effective date, making the impact more concentrated than when spread over the average daily trading volume. Strategy's size has also changed dramatically; according to the MSCI list, its free-float adjusted market capitalization has increased from approximately $23.9 billion in the May simulation to approximately $40.3 billion.
Judging from the scale of the sell-off alone, Strategy's claim that the new rules will not have a substantial impact seems to hold water.
The problem lies in the boundaries of the business. In addition to holding Bitcoin, Strategy's business also includes continuously raising funds to buy more Bitcoin.
In its filing with the SEC, Strategy stated that it listed index exclusion as a risk factor in both the first and second quarters of this year's 10-Q. It said that if MSCI or other major index publishers exclude it, or take measures such as delaying inclusion or restricting index-related adjustments, funds tracking the index may be forced to sell or buy less of its Class A common shares, which could have a significant adverse impact on the price and liquidity of its Class A common shares and other listed securities.
JPMorgan Chase also pointed out last year that while active managers are not obligated to follow index adjustments, being removed from major indices will certainly be viewed negatively by the market and raise concerns about Strategy's future equity and debt financing costs and capabilities. Bloomberg believes that the new regulations add new pressure to the financing model behind Saylor's massive Bitcoin holdings.
This financing model had already begun to distort. Bloomberg reports that as the premium of common stock relative to Bitcoin holdings disappeared, Strategy shifted to issuing perpetual preferred stock that did not dilute common stock equity, with a current outstanding balance of over $14 billion. However, its floating-rate preferred stock, STRC, has not been issued since May, and the company has instead repurchased over $1 billion worth of its own shares.
According to research firm K33, STRC increases Strategy's annual dividend obligations by approximately $725 million, equivalent to about 8,740 Bitcoins at $83,000 each. K33 believes the preferred stock financing model is a mistake and prefers Strategy to raise funds through methods such as common stock ATMs.
Strategy was also forced to sell Bitcoin earlier this year and announced plans to potentially sell Bitcoin from time to time to raise up to $1.25 billion for dollar reserves, preferred stock dividends, interest expenses, or share buybacks. Saylor is seeking to change preferred stock dividends from semi-monthly or quarterly payments to daily payments, with shareholder voting closing on October 28.
Meanwhile, buying activity at the industry level is also contracting. A report from Bitcoin financial services platform River shows that companies have net purchased 193,000 Bitcoins this year, with Strategy and Strive adding a combined 197,000, exceeding the total net purchases by companies. Other Bitcoin treasury companies, however, have only purchased a combined 8,000 Bitcoins.
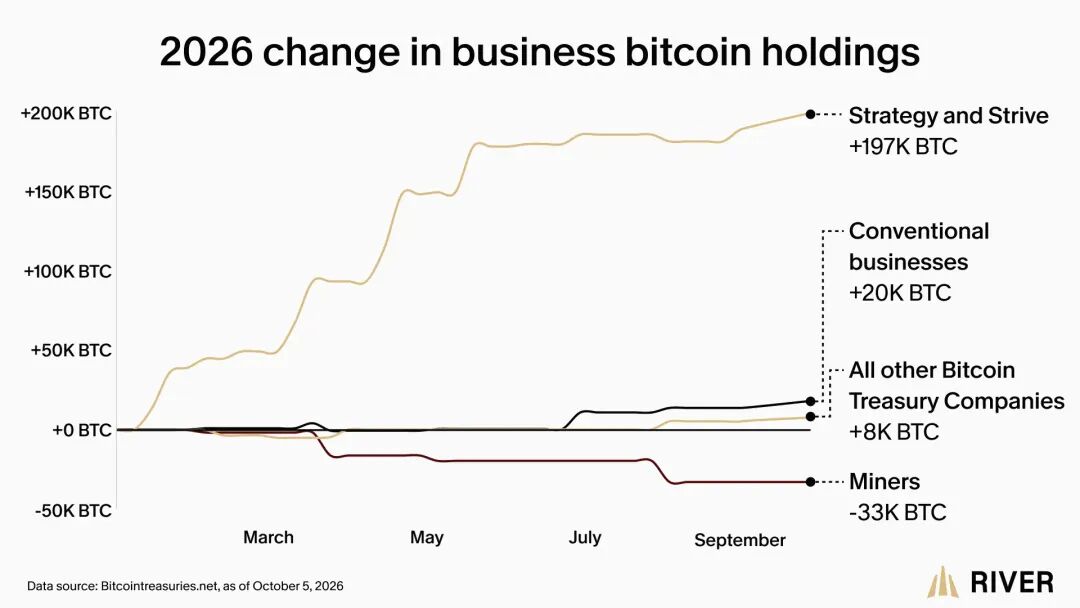
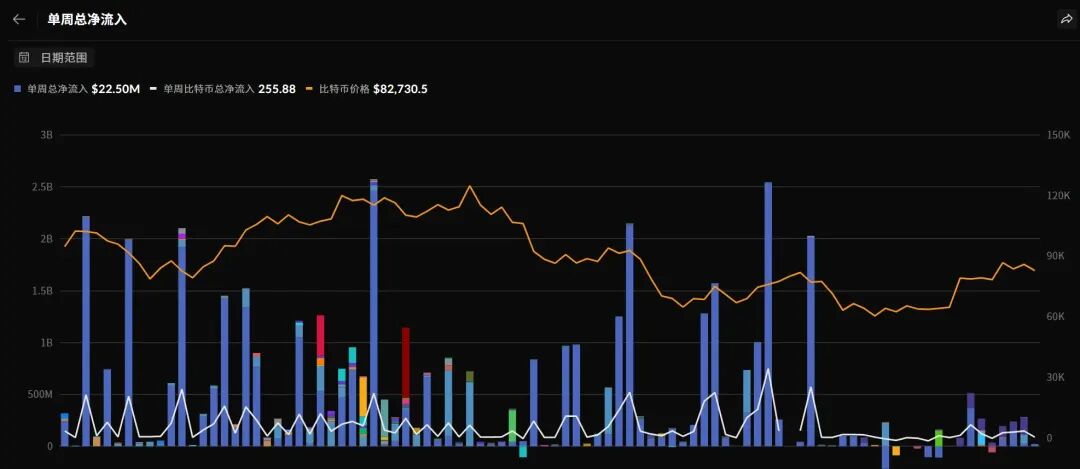
According to SoSoValue data, in the week ending October 12, global publicly traded companies excluding mining companies made a net purchase of only $22.5 million in Bitcoin, a decrease of 90.6% compared to two weeks earlier.
The same logic applies to Metaplanet. CEO Simon Gerovich disclosed that the company just announced the issuance of ¥52 billion in zero-coupon convertible bonds maturing in 2031, and is simultaneously pushing forward with share buybacks, also relying on external financing for expansion.
The difference is that Metaplanet is an MSCI small-cap stock with a free float adjusted market capitalization of approximately $800 million, and the amount of passive funds involved in its removal is far smaller than that of Strategy.
Returning to the initial question, a one-off sell-off may have a limited impact, as Strategy suggests, but for a company that increasingly relies on capital market funding, the cost of losing passive buying power may not become apparent until the next round of financing.
Source:Global Cybersecurity Alliance (GCSA)
Website:www.gcsa.org
Đăng ký tin, gửi thẳng vào hộp thư
Chúng tôi tôn trọng quyền riêng tư của bạn. Xem Chính sách quyền riêng tư