The money spent on chip purchases has circled back to Nvidia: Who's footing the bill for the revenue on paper?
In 2026, the four major tech giants, along with other players, will spend approximately $750 billion in capital expenditures, with about three-quarters of that going towards AI. This money is being spent, not earned.
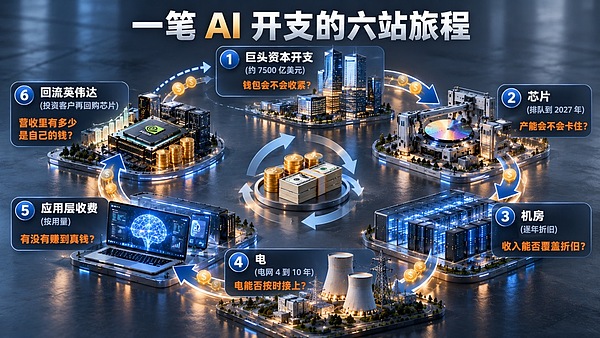
However, in the financial reports of upstream suppliers, it appears as impressive revenue figures, part of which is money that the chip-selling companies themselves invested and then received back. We traced this money through six points: the giants' wallets, chips, data centers, electricity, the application layer, and finally back to Nvidia. At each point, we asked only one question: With the money here, will it run out?
750 billion is expenditure, not revenue.
Nvidia's CEO made a point during the 2026 earnings call: computing power equals revenue. Whoever controls the most computing power controls the printing press. This chip company once boasted a market capitalization exceeding $5 trillion, surpassing the annual GDP of most countries in the world.
The fuel for this money-printing machine comes from the capital expenditures of giants. Capital expenditures are the money a company spends on buildings, equipment, and machinery for long-term operation. In 2026, Amazon plans to spend approximately $200 billion, Google's parent company approximately $180-190 billion, Microsoft approximately $190 billion, and Meta approximately $125-145 billion.
The four companies together have a combined total of $700 billion, and with other players, the total is approximately $750 billion. It is estimated that about three-quarters of this is directly invested in AI.
The tech giants buy chips and build data centers; the money spent on chip purchases is Nvidia's revenue. Therefore, our assessment is that the prosperity of the upstream sector is nurtured bit by bit by the midstream giants. Once they slow down their feeding, the upstream figures will change accordingly.
Money always flows to the scarcest and most irreplaceable links.
This statement is the key to understanding the entire chain. The party that blocks others can sit back and collect money; the party that is blocked loses its bargaining power.
Let's start by outlining the main theme of the entire article. In this cycle, every step involves quick payments and slow returns. Chips become obsolete in three or four years, while data centers depreciate over many years. Buildings can be completed in two years, but the power grid takes four to ten years. A model company's annual revenue is only in the tens of billions of dollars, yet it carries multi-year commitments that are an order of magnitude larger.
Therefore, there is only one standard for verification: has the application layer shifted from per-user pricing to usage-based pricing, and has it made real money? If the demand is genuine, this circle is collaborative; if the demand is false, it becomes a lever that accelerates collapse. At each subsequent stage, we will examine two things: whether the money is stuck here, and whether the money will be cut off here.
In the chip industry, money is lining up.
In the semiconductor industry, money will never run out; money will be lining up.
Many people believe that the bottleneck lies in chip design. In fact, the equipment for manufacturing chips requires decades of technological accumulation. For example, if a mirror inside a lithography machine were magnified to the size of Germany, the highest protrusion on its surface would not exceed 1 millimeter. Such precision is unmatched, no matter how much money you have.
After equipment comes manufacturing. The vast majority of chips developed by Nvidia, AMD, and other major manufacturers are sent to TSMC's production lines for production. The manufacturing process of a single chip has already approached its physical limits, forcing the industry to find another way to improve performance.
The real bottlenecks lie in packaging and memory. Advanced packaging tightly integrates several chips and memory modules like building blocks, minimizing data transmission. High-bandwidth memory is like a high-speed grain depot for the chips; if the grain depot can't keep up, even the most powerful chips will just be spinning idly. In 2026, production capacity for these two areas was extremely tight: advanced packaging was so tight it restricted customer growth, and most of the storage manufacturers' 2027 output was already locked in. The extent to which global AI computing power can increase annually is thus constrained by these two processes.
Nvidia has no say in how many chips it wants to sell.
Demand remains strong. Nvidia's data center business recently generated nearly $90 billion in revenue in a single quarter, with a year-on-year growth rate exceeding 100%. Its competitive advantage lies not only in its fast chips, but also in the code and habits that global engineers have built upon its software ecosystem over the past decade. Even if other companies develop more powerful or cheaper chips, the cost for customers to switch ecosystems is extremely high.
But customers are also looking for alternatives. The first is AMD. Even if it's weaker, as long as it exists, customers have more leverage at the negotiating table. The second is custom chips: giants commission Broadcom to design custom chips for them, and Broadcom aims for this business to reach a scale of hundreds of billions of dollars.
Our assessment is that the biggest variable in the chip industry lies in the development of in-house chips by major manufacturers. This is a collective attempt by these major companies to break free from Nvidia's dominance. The money is still lining up, but those already waiting are already looking for alternative solutions.
In the server room, money is getting old.
The $750 billion is not a one-time expense. In accounting terms, it will become an asset that depreciates over the years.
Depreciation is the process of spreading the cost of purchasing equipment over several years. Equipment purchased for $200 billion will gradually eat into profits over the next few years.
The harder you smash things today, the heavier the depreciation will be in the next few years.
What's more problematic is the speed. AI chips are updated extremely quickly; flagship chips from three or four years ago are no longer desirable. This means that the actual depreciation rate of devices may be faster than the book depreciation.
This is the first instance of a time mismatch: money is paid out quickly, value depreciates rapidly, but revenue returns are slow. Before a machine has even recouped its cost, the next generation of chips is already on the market, and customers naturally prefer to lease new ones. Therefore, the market's focus has shifted. In the past, the question was how much money was spent this year; now, the question is whether that money has translated into real revenue sufficient to cover depreciation.
If one day everyone finds that they've spent money and built buildings, but can't rent out the data centers or recoup their costs, then the pressure from this issue will directly impact the financial statements of the giants.
Another type of player in this market is the data center real estate developers who specialize in building server rooms. They are only responsible for constructing the buildings, connecting the network and electricity, and then renting out the server spaces to others to host servers, making a living from rent. Both the giants build and use their own facilities, and the real estate developers rent them out, but both models face the same problem: can the rental income keep pace with depreciation?
Our assessment is that the money for the data center won't suddenly stop, but it will gradually become obsolete in the accounts.
The electricity station is waiting for the power grid.
If chips are queuing up, then electricity is waiting.
A large AI data center operating at full capacity consumes the equivalent of a small city's worth of electricity. In the United States, data centers account for approximately 6% of the nation's total electricity consumption. Industry predictions suggest this could rise to 20% by 2035, meaning that one out of every five kilowatt-hours of electricity is used to power data centers. However, the sheer volume of electricity used isn't the most critical issue; the most critical factor is the time lag.
Building a data center takes about two years. Providing the necessary power grid, substations, and transmission lines can take four or even ten years. This leads to the absurd situation where brand-new server rooms, filled with chips, are left idle due to insufficient power.
This is the second instance of a time mismatch: the building was constructed quickly, but the electricity was connected slowly.
Data centers don't need cheap electricity; they need stable power. Wind and solar power are reliant on the weather; they shut down when there's no wind or sunlight. A single power outage while training large models can result in losses of millions of dollars. Therefore, baseload electricity with a stable supply around the clock is the most valuable, making nuclear power the most advantageous option.
One of the largest nuclear power operators in the United States has signed long-term power supply agreements with tech giants and even plans to restart closed old nuclear power plants specifically to power AI data centers. An even more radical approach is called off-grid power supply: building the data centers directly next to the power plant, with electricity bypassing the public grid and transmitted directly through the walls. This method was developed out of necessity due to the slow approval process for grid approvals.
Besides electricity, there's also heat. Tens of thousands of chips crammed together can't be cooled by ordinary fans; liquid cooling is essential. Liquid cooling, power supply, and temperature control equipment are the most inconspicuous yet most fundamental links in this chain.
A discerning observer will shift their focus from the chip itself to electricity and heat dissipation.
However, this bottleneck also has its limits. Some power stocks have more than tripled in the past three years, the entire logic built on the assumption that AI capital expenditures will always grow. Our judgment is that once spending slows down, this sector will be the first to feel the pressure. Electricity is a real bottleneck, but a bottleneck doesn't mean it won't be interrupted.
Only at this toll station can you recoup your money.
The previous stages all involved spending money; only the application layer is where real profits are generated. If AI can't make real money here, the previous prosperity is just a castle built on sand.
The watershed moment here is the pricing model. Traditional software charges per user: a company with 100 employees buys 100 accounts and pays annually. But if AI can replace employees, why would a company need to buy so many accounts? The market once worried that AI would become the gravedigger of traditional software companies.
The solution is to switch to a usage-based pricing model: the price is based on how many tasks the AI agent processes and how many times it is invoked. This way, the more heavily a company uses AI, the more the software company earns. Our assessment is that per-capita pricing will be consumed by AI, while usage-based pricing will be amplified by AI.
Some companies have already jumped ahead. Palantir has spent over two decades creating digital twins for enterprises, enabling AI to understand every machine, every order, and every employee. In the second quarter of 2026, its quarterly revenue approached $2 billion, representing a year-over-year growth of over 90%. Salesforce's AI agent platform specializes in sales and customer service automation, charging on a pay-as-you-go basis, and its latest annual recurring revenue exceeded $1.5 billion, representing a year-over-year growth of over 200%. ServiceNow goes even further, aiming to be a general contractor, helping enterprises to uniformly schedule, manage, and audit AI agents from different vendors.
Some companies didn't make the leap. C3.ai was once highly anticipated, but it failed to produce monetization data and didn't complete the transformation of its charging model, resulting in a significant drop in its valuation. Simply telling stories and talking about concepts won't work at this stage.
To judge whether an application company has real capabilities, don't look at promotional videos; look at only one metric: has it actually received more money because of AI? Some organizations predict that the global AI software market will grow from approximately $290 billion in 2025 to approximately $386 billion in 2026. However, our judgment is that the money will increasingly concentrate in the hands of a few companies that have successfully transformed their businesses.
A good company and a worthwhile price are two different things.
There's another point to clarify: most of the core, large-scale companies are not publicly listed, and their value is locked in the private market. What retail investors buy in the secondary market are companies that are related to the brain, not the brain itself.
The money circled back to Nvidia.
Originally, money flowed in one direction: tech giants spent money to buy Nvidia's chips, and Nvidia made money. In 2026, this one-way chain was welded into a closed loop, piece by piece.
We'll just state the facts. Nvidia initially announced plans to invest up to $100 billion in OpenAI, but what actually materialized was approximately $30 billion in equity investment. OpenAI subsequently signed large cloud and chip procurement contracts, with the money ultimately flowing back into Nvidia's chip supply. Nvidia also holds equity stakes in top modeling companies like OpenAI and Anthropic, totaling approximately $40 billion.
Nvidia invests money in its customers, who then use that money to buy Nvidia chips, ultimately resulting in impressive revenue on its financial statements. This model is called circular financing.
Before the dot-com bubble burst in 2000, telecom equipment manufacturers Lucent and Nortel did the same thing. They lent money to customers, who used the loans to buy their equipment. Revenue soared until customers went bankrupt and couldn't repay the loans, turning sales revenue into bad debt. The entire chain broke down, and many of these giants never recovered.
But this prosperity is borrowed.
How large is it today? Some analysts estimate that by 2026, the scale of such intertwined cyclical arrangements could exceed $800 billion.
Another set of figures looks at revenue. Some organizations estimate that by 2030, the entire AI ecosystem will need approximately $2 trillion in real revenue annually to support current investments; based on the current trajectory, the revenue gap could reach as high as $800 billion. The first $800 billion figure is a cyclical arrangement, while the second is a revenue gap; the two are not the same thing.
Now let's look at OpenAI. Its annual revenue is in the tens of billions of dollars, which sounds like a lot. But it has multi-year computing power purchase commitments that are an order of magnitude larger than its annual revenue, and it's currently still incurring substantial losses. On one hand, there's annual revenue, and on the other hand, there are multi-year commitments; there's a deep gap in between. This gap needs to be filled by future revenue, and future revenue is precisely the most uncertain part of this whole situation.
There's an even deeper, more fundamental question. The giants dare to spend money like this because they believe in the law of scale: the more computing power, the more data, and the larger the model, the smarter the AI becomes. This law hasn't been disproven, but no one can prove it will always be effective. Once the "the more you burn, the smarter" mentality fails, the entire valuation system will need to be repriced.
Those who are bearish argue that money is circulating idly within small circles, inflating revenue figures like balloons. If any link breaks down—for example, if OpenAI can't repay its loans, or if a major player drastically cuts spending—the balloon will burst. Too many companies are betting their performance on the assumption that data centers will continue to be built indefinitely; their fortunes are intertwined, leading to a chain reaction of pressure.
Those who are bullish say this time is different from 2000. These types of transactions represent a limited percentage of Nvidia's annual revenue and are insufficient to cripple the company. The $750 billion is for real chips, real data centers, and real electricity. Some organizations estimate that once generative AI is fully implemented, it could bring an annual value increase equivalent to 2.8% to 4.7% of a bank's annual revenue.
Furthermore, a signal emerged in 2026: for the first time, the demand for inference exceeded the demand for training. Inference refers to the calls generated each time you and I actually use AI. This indicates that AI is moving from the laboratory to large-scale real-world applications.
Our assessment is that the evidence from both sides is genuine, and the closed loop itself is not the original sin; the problem lies in the timing: at each stop, money is paid quickly but returned slowly.
Keep an eye on the cash register
All the stations ultimately lead to the same place: the cashier. From sand to computing power, from server rooms to electricity, from models to applications, and finally to the circle that connects all the money, we can conclude with three sentences.
First, a closed loop is an amplifier, not an engine. If the demand is real, this loop represents a sophisticated industrial collaboration; if the demand is fake, it becomes a lever that accelerates collapse. Therefore, what we really need to focus on is always the most basic application layer: has it shifted from per-user pricing to usage-based pricing, has it generated real revenue, and are more and more people and businesses becoming reliant on it?
Revolving financing is an amplifier, not an engine.
Second, the further upstream you are, the more certain the market becomes, but also the more crowded and expensive it is; the further downstream you are, the greater the volatility, but also the easier it is to be proven wrong. Upstream prices are already set at a very high level. Downstream prices could increase tenfold, or they could fall by half in a single quarter if they fall short of expectations. Understanding which risk you are willing to take is more important than chasing which narrative.
Cheap, certain, and high-potential—you can't have all three.
Third, be wary of narratives and track cash flow. When evaluating an AI company, ask three of the most difficult questions: Is revenue growth genuinely healthy? Can this growth be sustained, or is it being propped up by one-off related-party transactions? Has the current valuation already overdrawn perfect expectations for the next ten years?
We also need to keep an eye on companies building data centers to see if their debt is ballooning. History has repeatedly shown that bubbles often burst first on the debt side of the balance sheet, not the revenue side.
Our assessment is that whether this money-making cycle will end depends not on how many chips Nvidia sells, but on whether there is more and more real money on the cash register.
In this crazy era, understanding itself is a form of protection.
Source:Global Cybersecurity Alliance (GCSA)
Website:www.gcsa.org
Berlangganan berita, langsung ke email
Kami menghormati privasi Anda. Lihat Kebijakan privasi